There is something happening in the financial world right now that I think every person approaching retirement should pay attention to.
It isn’t whether the stock market finishes up or down this week.
It isn’t whether the Federal Reserve changes interest rates.
And it isn’t whether the latest economic prediction turns out to be right.
It’s uncertainty.
Right now, investors are watching inflation, interest rates, government debt, oil prices, geopolitical events and the direction of the economy—all at the same time.
Long-term interest rates have recently climbed to levels we haven’t seen in many years. Inflation remains a concern, and financial markets are watching this week’s economic reports and the Federal Reserve’s Jackson Hole symposium for clues about what comes next.
That leads to a question I believe is much more important than trying to predict the next move:
What if your retirement plan doesn’t need you to predict it?
Retirement Planning Has a Prediction Problem
People often approach retirement planning by trying to figure out what will happen next.
Will interest rates fall?
Will the market continue higher?
Will inflation finally settle down?
Should I move money now or wait?
Will taxes be higher ten years from now?
Those are reasonable questions.
But there’s a problem.
Nobody knows all of those answers.
And if your retirement depends on correctly predicting them, you may be taking on a risk you didn’t realize you had.
A better question may be:
How does my retirement work under several different futures?
That’s where retirement planning becomes much more interesting.
Imagine Three Different Retirements
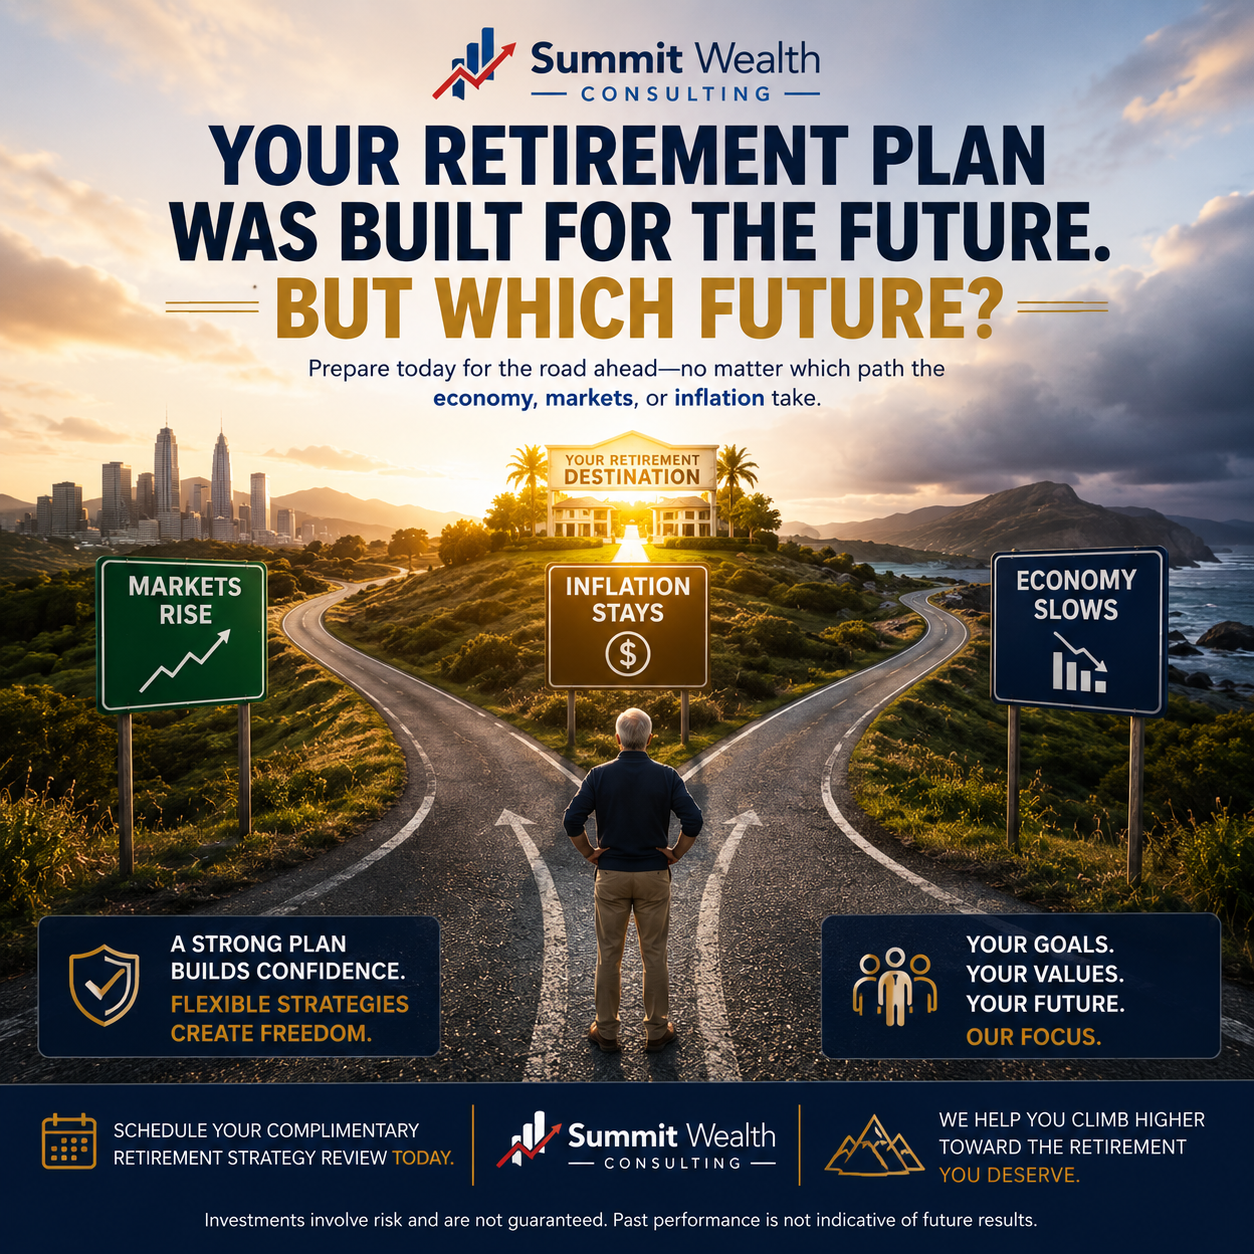
Let’s forget predictions for a moment.
Instead, imagine three possible versions of the next decade.
Future #1: The Market Does Extremely Well
Stocks continue growing.
Inflation settles down.
The economy remains strong.
Your investments perform well.
Wonderful.
Your retirement strategy should allow you to participate in growth and potentially benefit from those favorable conditions.
But that’s only one future.
Future #2: Markets Become Unpredictable
The market rises sharply one year and declines the next.
Interest rates move around.
Economic headlines create uncertainty.
Your retirement income still needs to arrive every month.
The mortgage company doesn’t care what the S&P 500 did.
Neither does the grocery store.
This is where income planning becomes different from simply accumulating investments.
When you were working, your paycheck funded your lifestyle.
When you retire, your assets may need to help create that paycheck.
That’s a completely different job.
Future #3: Inflation Stays Stubborn
This may be one of the most underestimated retirement risks.
Inflation doesn’t have to be dramatic to cause problems.
It simply has to continue.
Suppose someone retires needing $6,000 per month.
That lifestyle may feel comfortable today.
But 10, 15 or 20 years later, the same lifestyle could cost considerably more.
This week, inflation is once again front and center as markets await the Federal Reserve’s preferred PCE inflation measure. Recent reporting shows inflation remains above the Fed’s 2% target, which is one reason interest-rate expectations remain so important to investors.
A retirement plan therefore shouldn’t only ask:
“How much income can I generate today?”
It should also ask:
“How might that income keep up with tomorrow?”
Now Add the Things We Can’t Put Into a Calculator
This is where retirement gets real.
Markets and inflation aren’t the only variables.
Maybe you retire earlier than expected.
Maybe you live to 97.
Maybe your spouse requires care.
Maybe you want to help a child financially.
Maybe you decide to move.
Maybe taxes change.
Maybe Social Security becomes a larger or smaller percentage of your retirement income than expected.
Maybe you want to travel more during your first ten years of retirement.
Life rarely follows the original spreadsheet.
That’s why I believe a retirement plan should be designed for adaptability, not perfection.
Build a Retirement With More Than One Lever
Think about the dashboard in your car.
You don’t have one gauge.
You have several because different information matters at different times.
Your retirement should work similarly.
Depending on your circumstances, your financial strategy could include different sources of income and assets designed for different purposes.
Social Security may provide one layer.
Pensions may provide another.
Investment accounts may provide growth and liquidity.
Certain annuity strategies may be considered for guaranteed lifetime income, subject to the claims-paying ability of the issuing insurance company.
Roth accounts may provide a source of qualified tax-free retirement distributions when IRS requirements are satisfied.
Cash reserves can help handle shorter-term expenses.
Life insurance may play a role in protection or legacy planning when appropriate.
None of these tools has to do everything.
The power may come from how they work together.
One of the Biggest Risks May Be Having Only One Strategy
Imagine entering retirement with nearly every dollar sitting in tax-deferred retirement accounts.
Or nearly everything exposed to market fluctuations.
Or the opposite—so much money positioned conservatively that inflation gradually reduces purchasing power.
Each situation creates a different risk.
Diversification shouldn’t only mean owning different investments.
Retirement diversification can also mean having different types of money available for different jobs.
Money for today.
Money for emergencies.
Money for growth.
Money designed to create income.
Money positioned for future tax flexibility.
Money intended for your legacy.
That’s not about predicting the future.
It’s about preparing for several versions of it.
Stop Asking “What’s Going to Happen?”
When clients ask me what I think the market, inflation or interest rates are going to do next, I understand why they’re asking.
We all want certainty.
But I think there’s a better retirement planning question:
“What happens to me if we’re wrong?”
If rates don’t fall?
If inflation stays elevated?
If the market declines?
If taxes increase?
If you live longer than expected?
If your expenses are higher than projected?
Those questions can reveal weaknesses that a simple investment projection may miss.
The Goal Isn’t a Perfect Retirement Plan
Because one doesn’t exist.
The goal is to create a retirement strategy with enough flexibility that you don’t have to completely rebuild it every time the financial headlines change.
Think about that for a moment.
Markets will change.
Presidents will change.
Federal Reserve policies will change.
Interest rates will change.
Tax laws will change.
Your health may change.
Your priorities may change.
And your retirement could last 20, 25, 30 years or longer.
Your strategy needs the ability to change with you.
One Question to Ask Yourself This Week
With everything happening in the financial world right now, don’t ask yourself:
“What should I do because of this week’s news?”
Instead ask:
“If the next ten years look completely different than I expect, does my retirement plan still work?”
If you’re not sure, that’s a conversation worth having.
At Summit Wealth Consulting, we help individuals and families look beyond account balances and investment returns to coordinate retirement income, investments, taxes, insurance and legacy planning into a strategy designed around their lives.
Because nobody knows exactly what the next 20 years will bring.
A strong retirement plan shouldn’t require you to.
Ready to find out how your retirement strategy might perform under different financial environments? Contact Summit Wealth Consulting to schedule a complimentary retirement planning consultation. Schedule a Consultation SWC Website Contact Us
This material is for educational purposes only and is not intended as individualized investment, tax, legal or insurance advice. Investment values can fluctuate and guarantees associated with insurance products are subject to the financial strength and claims-paying ability of the issuing insurer. Consult the appropriate financial, tax and legal professionals regarding your individual circumstances.