The retirement risk hiding inside CDs, money markets and high-yield savings accounts
For the last few years, retirement savers have enjoyed something they hadn’t seen in a long time:
Cash actually paid something.
Money market accounts, CDs and high-yield savings accounts offered attractive yields without the daily swings of the stock market.
For retirees and those approaching retirement, it felt pretty good.
Why take additional investment risk when you could earn a respectable return while keeping your money relatively accessible?
But there’s a problem.
That interest rate isn’t yours forever.
And for retirees who have quietly started depending on that interest as part of their retirement income, the next financial surprise may not be a stock market crash.
It could simply be a CD coming due.
The $100,000 Question
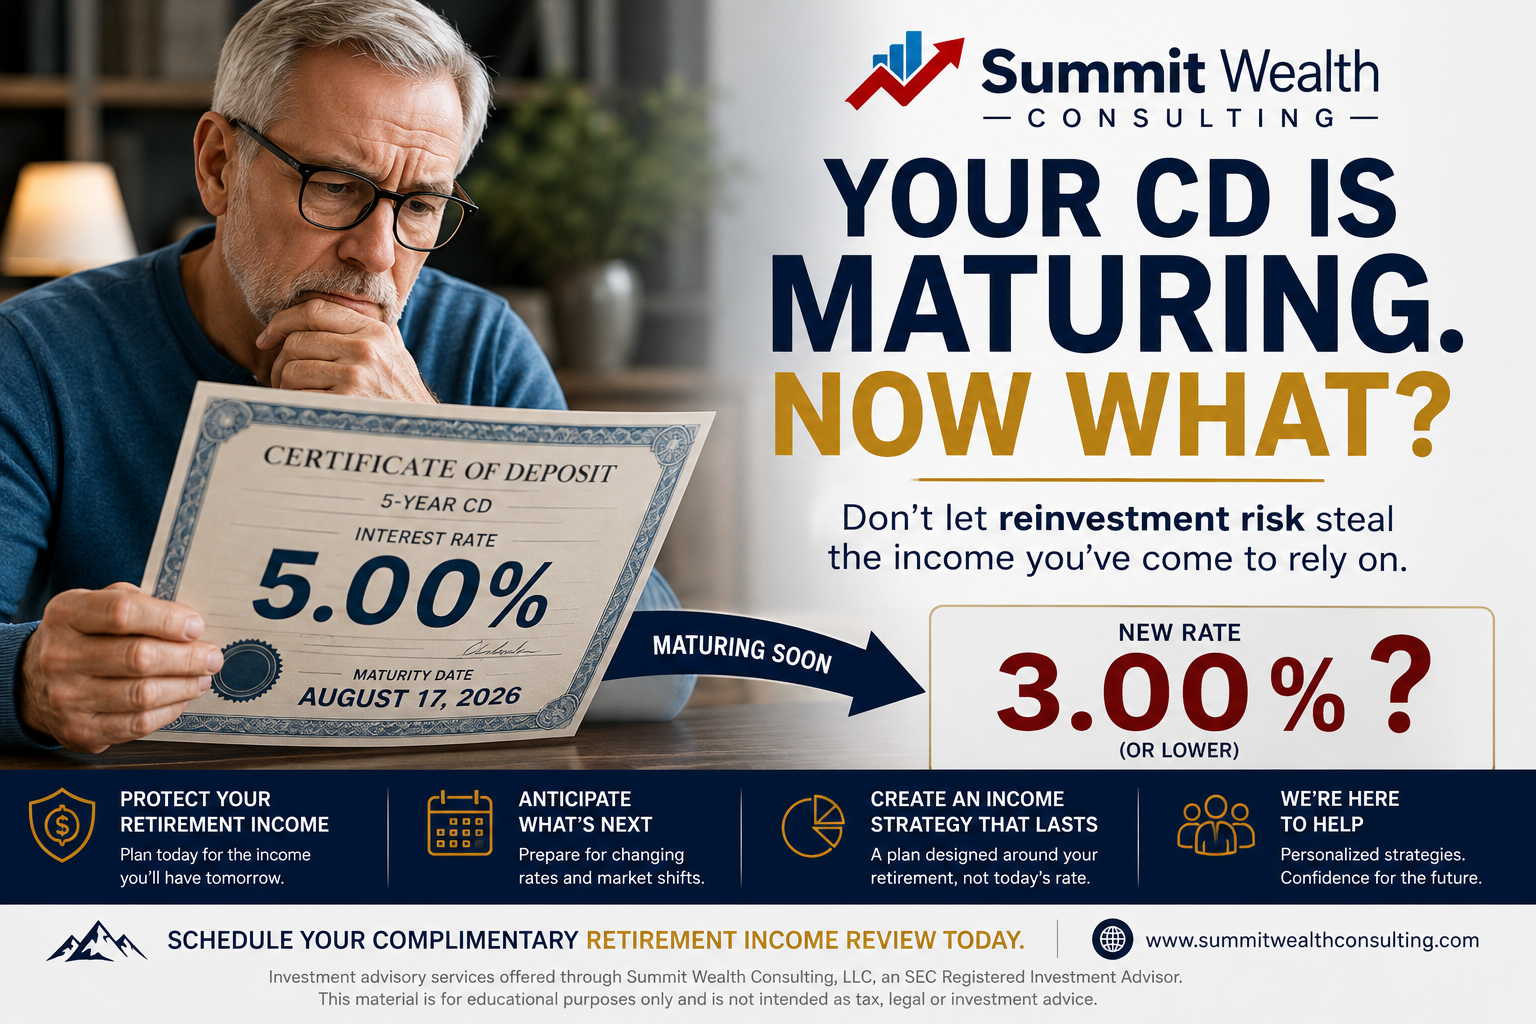
Imagine you placed $100,000 into a CD when rates were higher.
The interest became part of your financial picture. Maybe it helped pay property taxes, insurance premiums, vacations or everyday living expenses.
Then the CD matures.
You open your bank’s website expecting to renew it—and discover that comparable rates are considerably lower.
Your principal hasn’t disappeared.
But part of your income has.
That’s called reinvestment risk: the possibility that when a short-term investment matures, you may have to reinvest the proceeds at a lower interest rate.
For someone accumulating wealth, that may simply be disappointing.
For someone living on retirement income, it can create a hole in the monthly budget.
America’s Cash Comfort Zone
This isn’t a small issue.
Recent reporting indicates that individual investors are holding enormous amounts of cash, with money-market yields still attractive enough that many people remain reluctant to move elsewhere.
And it’s easy to understand why.
Cash feels comfortable.
You can see the balance.
It doesn’t fall 10% because of a bad week on Wall Street.
There is no complicated investment story to understand.
But there’s an important distinction:
Cash can provide stability. That doesn’t necessarily make it a long-term retirement income strategy.
If rates decline, the income generated by that cash can decline with them. BlackRock’s 2026 income outlook specifically identifies falling short-term yields as a reason retirees may need to reconsider how they generate durable income.
The Question Isn’t “Should I Have Cash?”
Absolutely.
Most retirement plans need liquidity.
Emergency expenses happen. Roofs need replacing. Cars break down. Healthcare bills appear. Opportunities arise.
The better question is:
How much of your retirement money needs to remain in cash—and what job is the rest of it supposed to do?
That’s a very different conversation.
Think about retirement assets as employees.
Every dollar should have a job.
Some dollars provide liquidity.
Some provide income.
Some pursue long-term growth.
Some may provide protection or guarantees, subject to the terms and claims-paying ability of the issuing institution.
Some may be positioned for future generations.
Problems can arise when too many dollars are assigned the same job simply because that job felt safest at the time.
The Retirement Income Mirage
Suppose a retiree has $500,000 sitting in various cash-equivalent accounts.
When rates are attractive, the interest can feel like dependable retirement income.
But there’s an important difference between:
income that happens to be available today
and
income you’ve strategically planned for tomorrow.
One depends heavily on whatever interest rates happen to be available.
The other begins with your expenses and asks:
How can we create a retirement paycheck designed to support those expenses throughout retirement?
That’s the conversation retirees should be having.
Don’t Chase Yesterday’s Yield
There’s another potential danger.
When people become accustomed to earning a certain rate, they sometimes go searching for that same yield after safer rates decline.
Suddenly an investor who was comfortable with a bank CD is considering investments or financial products they don’t fully understand simply because the advertised yield looks familiar.
That’s where caution matters.
Higher yield generally comes with additional considerations or risks.
Credit risk.
Market risk.
Liquidity restrictions.
Longer commitments.
Fees.
Complexity.
The goal shouldn’t be to replace a 5% CD with anything else paying 5%.
The goal should be determining what role that money needs to play in your overall retirement strategy.
Maybe Your CDs Need a Retirement Plan Too
Here’s an exercise worth doing.
Write down every CD, savings account, money market account and short-term investment you own.
Next to each one, write:
Amount | Interest Rate | Maturity Date | Purpose
That final column may be the most important.
Why do you own it?
Emergency reserve?
Next year’s living expenses?
Future home purchase?
Money you’re afraid to invest?
Retirement income?
Money you simply haven’t made a decision about yet?
You might be surprised how much money doesn’t actually have an assigned purpose.
Build an Income Strategy Before Rates Make the Decision for You
Interest rates will change.
Markets will change.
Tax laws will change.
Your spending will change.
Your health may change.
Your retirement strategy therefore needs something more valuable than today’s highest available interest rate:
flexibility.
Depending on your circumstances, that could mean evaluating cash reserves, CDs, bonds, Social Security, retirement-account withdrawals, tax strategy, investments and potentially guaranteed-income solutions together rather than making each decision independently.
There is no universal formula.
And that’s precisely the point.
Your retirement income plan should be designed around your retirement, not around whichever financial product happens to offer the highest yield this month.
One Question to Ask This Week
Look at the income currently being generated by your cash, CDs and money-market accounts.
Then ask yourself:
“If these rates were meaningfully lower when my money comes due, would my retirement plan still work?”
If you don’t know the answer, that’s worth finding out.
Because today’s interest rate is temporary.
Your retirement isn’t.
At Summit Wealth Consulting, we help individuals and families look beyond individual accounts and build coordinated retirement strategies around income, taxes, investments, protection and long-term goals.
If a significant portion of your retirement savings is sitting in cash, CDs or money-market accounts, this may be an excellent time to determine what that money should be doing next.
Schedule a complimentary retirement income review with Summit Wealth Consulting. Schedule a Complimentary Retirement Review
Let’s make sure your retirement income strategy is designed for more than today’s interest rate. Contact Us SWC Website