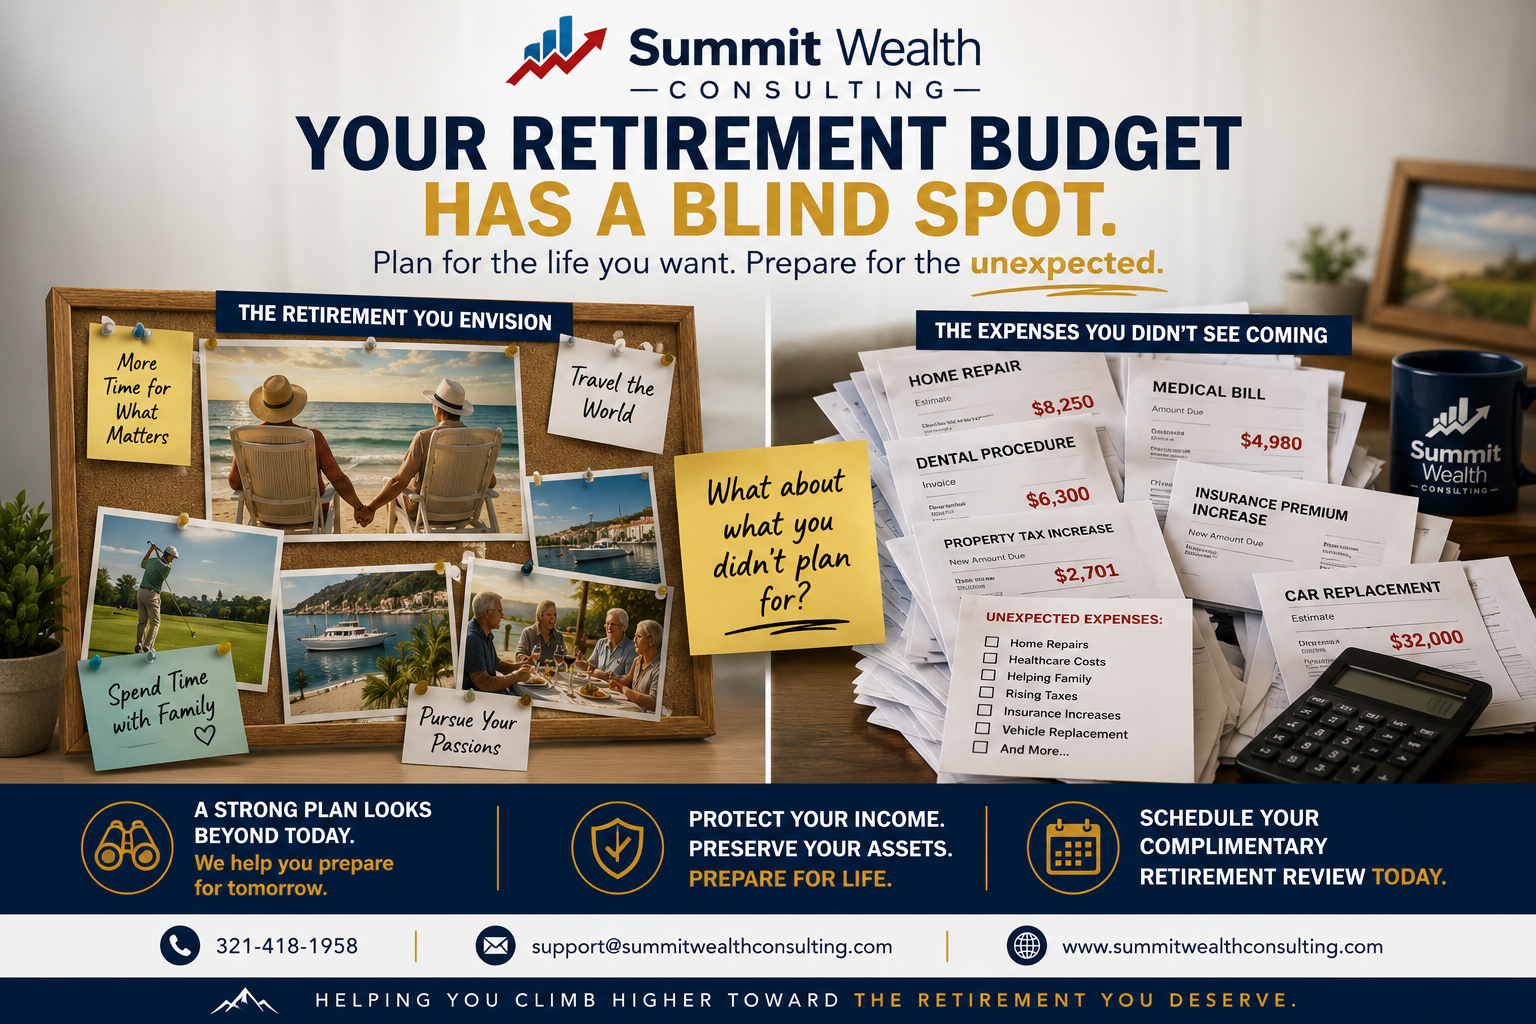
Your retirement plan may account for vacations, golf and dining out. But what about the expenses you never planned to have?
When most people picture retirement, they don’t picture a spreadsheet.
They picture freedom.
Maybe it’s morning coffee overlooking the ocean.
Finally taking that trip to Italy.
Spending more time with grandchildren.
Playing golf on a Wednesday afternoon simply because you can.
That’s the retirement people plan for.
But there’s another retirement budget that doesn’t make it onto the vision board.
The new roof.
The $8,000 dental procedure.
The adult child who suddenly needs financial help.
The insurance premium that jumps again.
The air conditioner that decides July is the perfect month to retire, too.
And here’s the problem:
Your retirement plan has to pay for both versions of retirement.
The Danger of the “Perfect Year” Retirement Plan
Retirement projections can look beautiful when every year behaves exactly as expected.
Your portfolio earns its projected return.
Inflation stays manageable.
Your spending remains predictable.
Nothing major breaks.
Nobody needs unexpected help.
Unfortunately, life doesn’t operate in averages.
A retirement lasting 20, 25 or 30+ years will probably include some expensive surprises.
And today’s retirees are already feeling pressure from expenses such as housing, healthcare, transportation and inflation. Recent analysis shows inflation-adjusted spending among households age 65+ has increased substantially over the past several decades, with housing representing one of the biggest pressures on retirement budgets.
That’s why retirement planning shouldn’t only ask:
“Can I afford my lifestyle?”
It should also ask:
“Can my plan absorb the years when life gets expensive?”
Surprise #1: Your House May Follow You Into Retirement
Many people enter retirement believing their home will become one of their greatest financial advantages.
And it certainly can.
But even a mortgage-free home isn’t expense-free.
There are property taxes.
Homeowners insurance.
Maintenance.
HVAC systems.
Roofs.
Plumbing.
Landscaping.
Renovations.
And as you age, you may eventually need modifications that make the home safer and easier to navigate.
A paid-off house eliminates the mortgage payment.
It doesn’t eliminate the cost of owning a house.
That distinction belongs in your retirement plan.
Surprise #2: Medicare Doesn’t Mean Healthcare Is Free
This one catches people.
You become eligible for Medicare and assume one of retirement’s biggest financial concerns has largely been solved.
Not necessarily.
Depending on your situation, retirement healthcare can include premiums, deductibles, copays, prescription expenses, dental care, vision care, hearing expenses and services that aren’t fully covered.
And healthcare spending doesn’t necessarily arrive evenly.
One year may be relatively inexpensive.
Another could be extremely costly.
That’s why healthcare deserves its own strategy rather than simply being buried inside a general monthly retirement budget.
Surprise #3: Your Children May Still Be on the Payroll
Here’s an expense few retirement calculators understand:
family.
Maybe your children are grown.
That doesn’t necessarily mean they’re financially independent forever.
A divorce happens.
Someone loses a job.
A grandchild needs tuition assistance.
There’s a medical emergency.
Your adult child needs help buying a home.
And because you’re Mom or Dad, you want to help.
There’s nothing inherently wrong with that.
But there’s an important question:
Are you helping your children from your surplus—or from your future?
Giving $20,000 to a child at age 67 doesn’t just cost $20,000.
That money also loses whatever future growth or income it might have generated throughout the remainder of your retirement.
Generosity should be planned whenever possible.
Surprise #4: Taxes Didn’t Retire When You Did
Many retirees are surprised to discover that retirement doesn’t necessarily mean lower taxes.
Traditional IRA and 401(k) withdrawals can generally create taxable income.
Social Security benefits may be taxable depending on your circumstances.
Investment income may have tax consequences.
Required minimum distributions can eventually force money out of certain retirement accounts.
And some income decisions can affect Medicare premiums.
That’s why two retirees with identical $1 million portfolios could potentially have very different amounts of money available to spend.
The number that matters isn’t simply:
How much have you accumulated?
It’s:
How much of it can you actually use?
Surprise #5: Inflation Doesn’t Need to Be Dramatic to Hurt
Inflation is particularly dangerous in retirement because it doesn’t have to arrive as one enormous expense.
It works quietly.
Groceries become slightly more expensive.
Insurance increases.
Restaurants raise prices.
Home repairs cost more.
Travel costs rise.
Healthcare increases.
One increase doesn’t necessarily change your lifestyle.
Twenty years of increases can.
Recent August 2026 retirement coverage has again highlighted inflation as a significant planning issue because it gradually reduces purchasing power, particularly for retirees whose income doesn’t rise alongside their expenses.
Consider something simple.
If your lifestyle costs $80,000 today, you shouldn’t automatically assume $80,000 will provide the same lifestyle 15 or 20 years from now.
Your retirement income strategy needs room to grow.
Surprise #6: One Car Can Become Two Financial Decisions
Vehicles don’t last forever.
If you’re retiring at 65 and planning for a 25- or 30-year retirement, there’s a reasonable possibility you’ll purchase several more vehicles during your lifetime.
That’s potentially tens of thousands of dollars each time.
Yet many retirement budgets include:
Gas.
Insurance.
Maintenance.
But not necessarily:
“Replace vehicle in seven years.”
Major purchases shouldn’t automatically become emergencies simply because they don’t occur every month.
The Expense Almost Nobody Budgets For: A Long Life
This might be the biggest one.
Living longer is wonderful.
Financially, however, longevity means your assets may need to support more years of:
Housing.
Food.
Healthcare.
Transportation.
Taxes.
Insurance.
Travel.
Family assistance.
And everyday living.
Retirement planning therefore isn’t simply about reaching age 65 with a certain account balance.
It’s about building a financial system capable of potentially supporting you into your 80s, 90s or beyond.
Create a “Life Happens” Retirement Fund
Here’s an idea I believe more retirees should consider.
In addition to your normal emergency reserve, identify money specifically intended for large irregular retirement expenses.
Call it whatever you want:
The Life Happens Fund.
The Retirement Surprise Account.
The “Of Course the Roof Broke” Fund.
The name doesn’t matter.
The purpose does.
Instead of treating every major expense as an unexpected disruption, you’re acknowledging something important:
Unexpected expenses are actually pretty predictable.
You don’t know exactly what will happen.
You simply know that over a long enough retirement, something probably will.
Stress-Test Your Retirement Before Life Does It for You
When we evaluate retirement income planning at Summit Wealth Consulting, one of the most valuable conversations isn’t simply:
“What return can your portfolio earn?”
It’s:
“What happens when life doesn’t go according to plan?”
What if inflation remains higher?
What if healthcare expenses increase?
What if you need a new vehicle?
What if you help your children?
What if the market declines during your first few years of retirement?
What if one spouse lives significantly longer than expected?
What if you live to 95?
A strong retirement strategy shouldn’t require everything to go perfectly.
It should be designed with enough flexibility to adapt when things don’t.
Your Retirement Should Have a Margin for Life
You’ve probably heard businesses talk about maintaining a financial margin.
Retirees need one too.
Because the objective isn’t to spend every available dollar according to a perfectly optimized projection.
It’s to create enough structure that an unexpected $10,000 expense doesn’t suddenly make you question whether your entire retirement is still secure.
That confidence can be incredibly valuable.
One Question to Ask Yourself This Week
Pull out your retirement plan and look at the expenses you’ve projected.
Then ask:
“Where is the money for everything I didn’t think of?”
If there’s no clear answer, that may be the most important retirement planning conversation you haven’t had yet.
At Summit Wealth Consulting, we help individuals and families look beyond the account balance and build retirement strategies designed around income, taxes, investments, protection and the realities of everyday life.
Because retirement isn’t going to follow a spreadsheet perfectly.
Your financial plan shouldn’t require it to.
Schedule a complimentary retirement planning consultation with Summit Wealth Consulting and let’s stress-test your retirement strategy before life does it for you. Schedule a Consultation SWC Website Contact Us
This material is provided for educational purposes only and is not intended as individualized investment, tax, legal or insurance advice. Financial strategies involve varying risks, costs and tax considerations. Consult the appropriate financial, tax and legal professionals regarding your individual circumstances.